The focus this week will be on the bond market this week…as earnings seasons is still a couple of weeks away. So, oil prices…and this week’s plethora of economic data will be the focus.
That said, a small number of tech stocks are the key for the stock market over the near-term. Whether they can continue to hold up or not will continue to be extremely important.
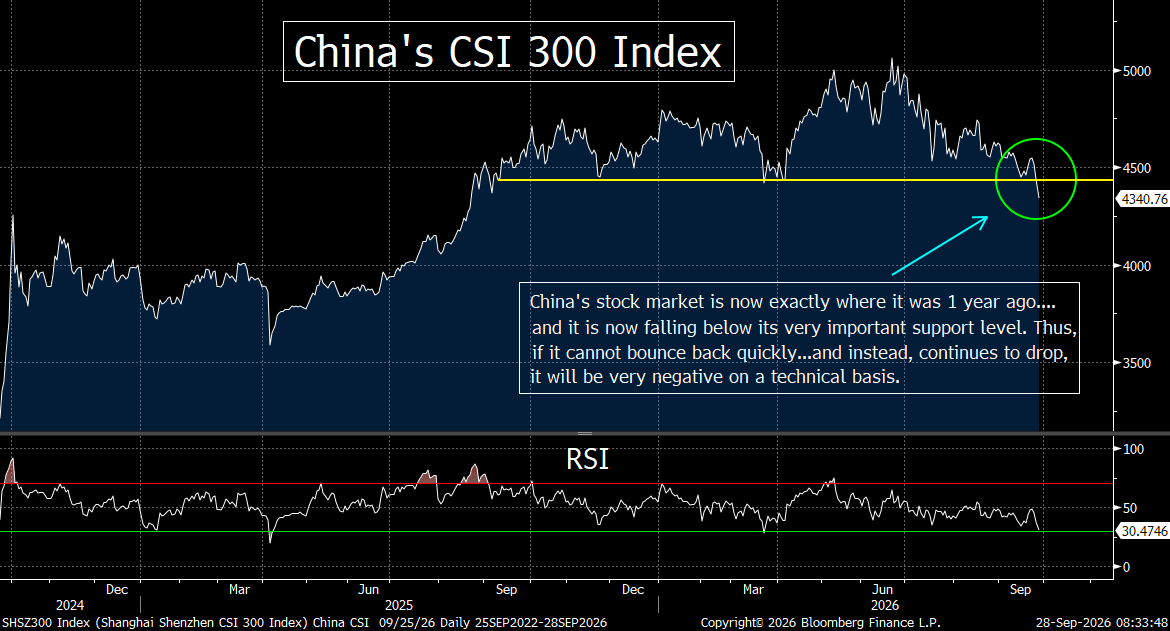
China’s stock market is breaking a key support level. So, if it doesn’t bounce back quickly, it will raise a warning flag on that market.
After a weekend of thrilling conclusions to many football games in college and the NFL…and the same in the Presidents Cup Golf Tournament…the markets are looking like they’ll see a lot of excitement this week as well. Since earnings season is still a couple of weeks away, the focus this week will be on economic data this week. We get the Core PCE inflation data on Wednesday…and we get several different readings on employment…with the biggest one coming on Friday (when the BLS reports their numbers on this issue)………On top of all this, we also have the geopolitical issues…and the moves in the price of oil.
On this latter issue, crude oil is up about 3% this morning. This is actually lower than it was overnight…as the announcement that the Saudi East-West pipeline has reopened has helped the price of crude all come down a little bit. However, the 3% rise that still exists as we write has still been enough to push the yield on the US 10-year note higher (above 5.2%)…and weigh on the equity futures in a material way.
That said, those stock futures are not falling out of bed. The S&P futures are down 0.4%, and the NDX futures are down 0.6%...so it’s not like we’re looking at melt down this morning. Besides, these two indices are both less than 1% from their all-time highs…so as much as the bond market has been in the middle of a horrible bear market this year, the stock market has been able to ignore it quite nicely.
The problem is that history shows that this cannot go on forever. As we have highlighted ad nauseam in recent weeks, every time we see the kind of rise in long-term yields that we’ve seen over the past year, it has always led to a significant decline in the stock market eventually…..Since this is something that more people on Wall Street are finally talking about, it could be something that impacts the stock market sooner rather than later. Given that earnings season doesn’t begin for a couple of more weeks, these higher yields should provide at least SOME headwinds this week.
We do need to point out that the Treasury market is getting oversold (overbought on yields)…and the same is true for the several other fixed income related ETF’s (like the HYG high yield ETF, and the LQD investment grade corporate bond ETF). However, since the movement in those markets seems to be so closely tied to the price of oil right now, they might not get much relief from their oversold conditions. As much as the Administration will likely spend a lot of time highlighting the existing of worthwhile “talks” between now and the midterm election, it does not look like anything significant will take place. As long as Iran insists on having control of the Strait of Hormuz, any dip in oil prices will likely be quite short-lived.
Having said all this, there is no guarantee that the eventual (inevitable?) impact of higher yields on the stock market will take place very soon. The stock market has been able to hold up quite nicely for several months in the fact of these rising yields…so they could continue to do so for a while longer. Besides, the midterm election is still 5 weeks away…and the Administration will want to keep the market buoyed until that time. Therefore, investors will want to remain very nimble over the near-term…but this week’s economic data should be even more important for the markets than usual.
Put another way, as much as the bond market should have a very important impact on the stock market eventually…the tech sector will continue to be extremely important for the near-term prospects for the stock market. Thus, we will continue to keep a close eye on the XLK technology ETF…as well as the SOX semiconductor index. As we highlighted in our weekend piece, both of these are not far from key resistance levels. So, if they can push higher between now and the midterms, the stock market should still be fine…at least for now. Let’s face it, if the past couple of weeks are any indication, we only need a handful of names to push higher (AAPL, AMZN, META, MSFT, NVDA, AMD & TSM.) …in order for the key indices to remain elevated. If, however, these few stocks DO start to see any material weakness, things will get quite dicey…quite quickly.
Finally, we just want to update the chart from our weekend piece on China’s stock market. Their CSI 300 Index fell 2.2% last night…and took it below the key support level we had highlighted this weekend. This is definitely a negative development for their stock market on a technical basis. Yes, it will take a bit more downside follow-through to confirm the breakdown…and this index is getting oversold. However, any further weakness in this market as we move into the month of October will definitely raise some big warning flag on China’s stock market. (Chart below.)